|
● September 2026
The Nashville
Market Update
Sample Loan Officer · Sample Mortgage Company
|
|
|
|
|
Today's average rates — Friday, September 25
|
CONVENTIONAL 30-YR 7.17% |
FHA 30-YR 6.88% |
JUMBO 30-YR 7.28% |
|
|
Source: Bankrate national survey, September 25, 2026.
|
|
|
Every month I pull together the numbers that actually matter for the Nashville metro. What is happening with rates, what homes are really selling for, and what it means for you whether you are buying, selling, or staying put. Here is September. It is a better market than the headlines make it sound.
|
So rates hit 7%.
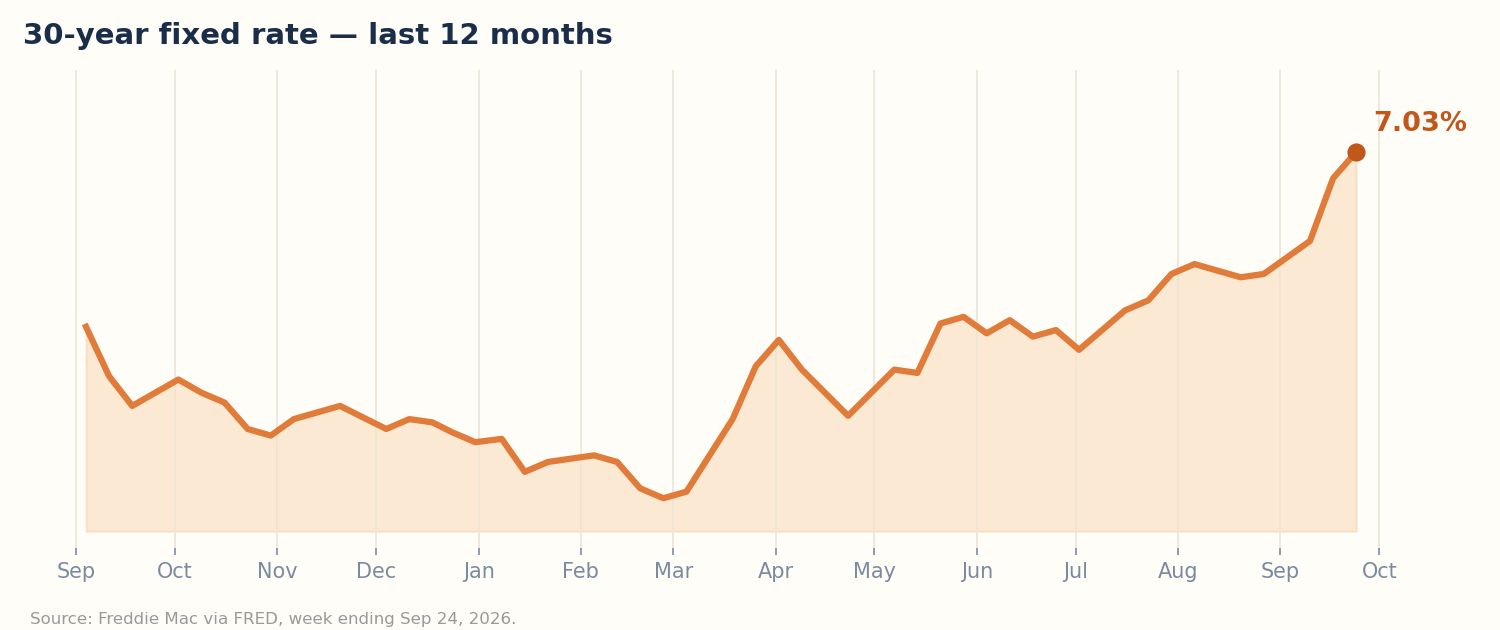
The average 30-year fixed came in at 7.03% this week in Freddie Mac's weekly survey. First time we have seen a seven handle since January of last year. If that number stings, I get it.
Here is how I look at it, though. For most of the last fifty years, rates were higher than this. The 2s and 3s of 2020 and 2021. That was the weird part, not this. And rates are not up because something is broken. They are up because the economy is humming: jobs are solid, wages are growing. Freddie Mac's chief economist said it plainly this week: the housing market is standing on a strong job market and a healthy economy.
So what does 7.03% cost in real dollars? On a $700,000 loan you are looking at around $4,671 a month in principal and interest. The same loan a year ago at 6.3% was about $4,333. Call it $340 more a month. I am not going to pretend that is nothing.
But I will tell you what I tell my buyers. Remember what 3% rates actually felt like? Twenty offers on every decent house. Waiving the inspection and praying. Offering over asking and still losing. Nobody misses that.
Right now the shoe is on the other foot. Sellers are negotiating. You can ask for closing costs. You can ask for repairs. You can sleep on a decision. Give me a higher rate on a house I negotiated a good deal on over winning a bidding war at 3% — every time.
|
“Give me a higher rate on a house I negotiated a good deal on over winning a bidding war at 3% — every time.”
|
And one more thing people forget: you do not marry the rate. Folks bought at 12 and 13% back in the eighties and refinanced their way down over the years. Buy the right house while nobody is competing with you — and if rates ease down the road, a refinance may be worth a look.
|
|
|
Rates drifted down through the winter, then climbed all summer to 7.03% — the first seven-handle since last January.
|
|
|
Nashville metro — the quick numbers
|
$539,900
Median list price
flat vs last year
|
|
|
12,197
Active listings
▲ 12.6% from last year
|
|
|
59 days
Median days on market
a balanced market
|
|
|
22%
Listings with price cuts
room to negotiate
|
|
Across the metro, more than one in five listings has taken a price cut — sellers are negotiating.
Source: Realtor.com Economic Research, Nashville metro data, August 2026.
|
Around the country
Two national stories caught my eye this month.
First, new construction. Sales of newly built homes jumped in August, the highest in eight months and way above what the experts predicted. Why? Builders are dealing. Price cuts, cheaper rates for the first couple of years, closing cost help, free upgrades. The median new home price dropped almost 6% from last year to $393,700. Down here in the South, new home sales were up about 7%. If resale prices have felt too rich for your blood, the new construction side deserves a look right now.
Second, inventory. There are more existing homes for sale across the country than we have seen in six years. About five months' worth, the most in a decade. That is buyer leverage, plain and simple. Sellers know it, and they are coming to the table.
And through all of it, prices keep inching up. The national median hit $429,100, up for the 38th month in a row. Slow and steady. That is the kind of appreciation that builds wealth without keeping anybody up at night. Wages have actually outrun prices over the past year, so affordability got a little better, not worse.
One more, for the optimists: builders broke ground on 918,000 single-family homes in August, up from 848,000 in July. Builders do not pour foundations unless they think buyers are coming. Read it as a vote of confidence.
|
If you are thinking about buying
I cannot remember the last time buyers had this much working in their favor.
Nearly 13% more homes to pick from than last year, right here in the Nashville metro. Sellers writing checks at closing. Less competition every fall, like clockwork. It is all lining up at once.
The play I keep coming back to: negotiate hard on the price now. If rates come down later, refinancing may be an option — but buy the house because the deal works today, not because of a maybe. A $20,000 price cut at 7% is worth more than most people realize. And you can only get that kind of cut when the seller needs you. Which is right now. Wait around for 6% and you will be fighting the whole crowd again.
Here is a tactic getting a lot of use: the 2-1 buydown. The seller pays to knock your rate down for the first two years. It is basically a discount on your monthly payment, paid for by the seller, and sellers are agreeing to them left and right in this market. If you want me to run the math on one, just ask.
Get pre-approved even if you are just browsing. Fifteen minutes, costs nothing. When the right house pops up, and with this much inventory it will, you will be ready instead of scrambling.
|
The bottom line: negotiate hard on the price now — buy it because the deal works today.
|
|
If you are selling
More competition out there: about 600 more homes listed than two years ago. But step back and look at the number that matters: the median sold price is up 3.3% from last year. Your house is worth more than it was twelve months ago. That is the headline.
The playbook right now is simple and it works. Price it for today's market on day one, not last year's. Make it look great. Be willing to give a little at the negotiating table. The houses collecting dust are the ones priced like it is still 2021. Price it right and 59 days on market, our median, is a totally normal sale.
This market suits serious sellers. The buyers showing up now are qualified and ready to move. Fewer bidding wars means fewer appraisals coming in short and blowing the whole thing up at the finish line.
|
The bottom line: price it for today's market on day one — 59 days is a perfectly normal sale.
|
|
If you already own
Your equity went up again. Up 3.3% here in the metro, up nationally 38 months running. Bought a couple of years ago? You are sitting on real money.
Put it to work or just enjoy knowing it is there. A renovation that adds value, wiping out high-interest debt, whatever fits your life. If your rate starts with a 3, 4, or 5, guard it with your life. Bought recently up in the 7s? Let us talk through what a refinance could look like down the road, so you know your options if rates move in your favor.
And stack it against renting: $3,200 a month is the county median now, and it keeps climbing. Owning wins that comparison going away.
|
The bottom line: your equity grew again — put it to work, or sit tight and enjoy it.
|
|
What I am watching
Two things on my radar. First, the Fed. Most of the folks over there are hinting at another hike before Christmas… Second, those builder incentives: price cuts, buydowns, closing cost credits. Best deals in the market at the moment, and they have a way of drying up fast once demand comes back.
Both worth keeping an eye on as we head into the holidays.
|
|
Wondering what any of this means for your own situation?
Just hit reply. I read everything, and I will give you a straight answer.
|
|
|
Sample Loan Officer
Sample Mortgage Company
(555) 010-0000 · NMLS #000000
|
|
Data sources: Bankrate national mortgage survey, September 25, 2026 · Freddie Mac Primary Mortgage Market Survey, week ending September 24, 2026 · Realtor.com Economic Research, Nashville metro data, August 2026 · National Association of Realtors, Existing-Home Sales, August 2026 · U.S. Census Bureau and HUD, New Residential Sales and Housing Starts, August 2026 · National Association of Home Builders, September 2026.
This newsletter is for general information only — not mortgage advice, and not a promise of any future rate, approval, or loan terms.
You are receiving this because you are on my market update list. To unsubscribe, just reply with the word UNSUBSCRIBE.
|
|